Show summary Hide summary
Social Security rules that change each year will shift again in 2027, altering benefit amounts, how much income is taxed, and some Medicare costs. These adjustments matter now because they affect retirement planning, take‑home pay for older workers who keep working, and the size of monthly checks received by millions.
Every November and December, the Social Security Administration and related agencies publish the official figures that set next year’s limits and rates. While the precise numbers for 2027 will be posted on SSA.gov and by the Centers for Medicare & Medicaid Services, the kinds of changes that take effect are predictable—and they have immediate implications for household budgets and tax planning.
How annual adjustments work
Social Security benefits set to shift in 2027: how your payments could change
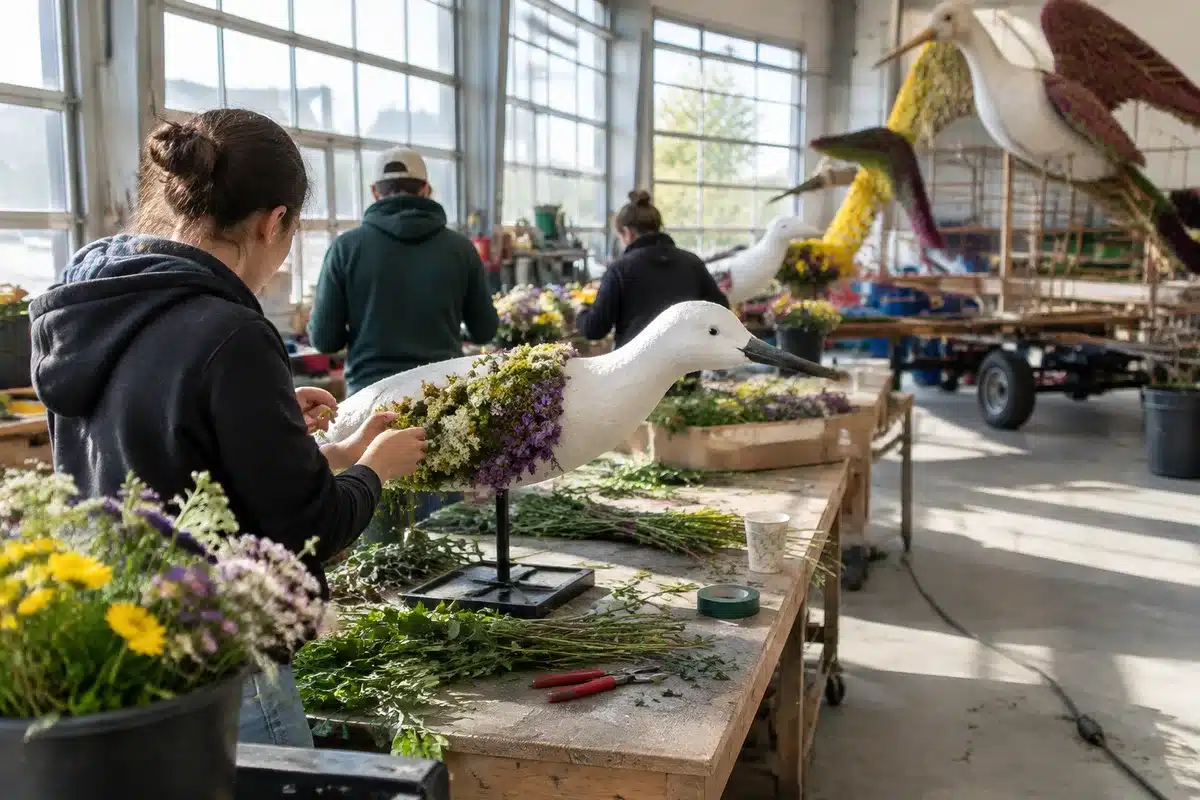
Cal Poly Rose Float picks 2027 theme: Soaring as One aims for unity
Social Security benefits are indexed to price and wage measures so that payouts and the program’s thresholds move with inflation and average earnings. That automatic updating affects several program features at once: the monthly Cost‑of‑Living Adjustment, the earnings cap subject to payroll taxes, and income rules that determine how work affects benefit payments.
Medicare costs and some related income‑based surcharges are adjusted separately by federal agencies. Because these updates are applied at the start of the year, decisions made now—about when to claim benefits, how much to withhold or defer, or whether to continue working—can change what you pay or receive in 2027.
Key items to watch for 2027
- Cost‑of‑Living Adjustment (COLA) – The annual COLA raises monthly benefits to reflect inflation. A higher COLA increases benefit checks but may also push some beneficiaries into higher tax or Medicare premium brackets.
- Maximum taxable earnings (Social Security wage base) – The amount of income subject to Social Security payroll tax typically rises with average wages. That affects both payroll tax bills and the maximum possible benefit for future retirees.
- Earnings limit for beneficiaries under full retirement age – Workers who claim benefits before reaching full retirement age can lose part of their benefit if they earn above the annual threshold; that threshold is adjusted each year.
- Medicare Part B and Part D costs – Monthly premiums, deductibles and income‑related adjustments are often changed for the new year and influence out‑of‑pocket healthcare spending for retirees.
- Supplemental Security Income (SSI) – Federal SSI payment levels are typically updated, which affects low‑income seniors and people with disabilities.
- Tax rules affecting benefits – While the basic thresholds for taxing Social Security benefits are set in law, changes in taxable income, deductions, or IRS brackets can alter whether and how much of your benefit is taxed.
What this means for workers and retirees
If you are still working and collecting Social Security, even modest changes in the earnings limit or COLA can affect whether part of your benefit is withheld and how much you take home. For people approaching full retirement age, small timing adjustments—delaying a claim by months—can increase long‑term benefits.
For current beneficiaries, a boost in the COLA helps with rising costs but can also raise Medicare premiums or push more of your benefits into taxable territory. Low‑income households relying on SSI should watch for changes to federal payment amounts that could affect eligibility for other programs.
Practical steps to take now
- Check the official 2027 figures on SSA.gov and CMS pages as soon as they’re released; those numbers determine exact dollar effects.
- Review your benefit statement and recent pay stubs to estimate whether wage changes will trigger the earnings limit or higher payroll taxes.
- If you’re nearing an important claiming milestone, run projections with different claiming dates or speak with a financial planner to compare lifetime outcomes.
- Consider tax withholding or estimated payments if a higher COLA or other adjustments might increase your tax liability on benefits.
Annual Social Security updates are routine, but their combined impact can be significant. Watching the official announcements and adjusting plans now will help households avoid surprises and make better decisions for 2027.